OPay’s $4 Billion Test: Africa’s Payments Giant Is Becoming a Lender Ahead of Its NYSE IPO
OPay’s $4 Billion Test: Africa’s Payments Giant Is Becoming a Lender Ahead of Its NYSE IPO
This voice experience is generated by AI. Learn more.
OPay’s $4 Billion Test: Africa’s Payments Giant Is Becoming a Lender Ahead of Its NYSE IPO
By WigWag Africa Business Desk
OPay built its business by making digital finance accessible through neighbourhood shops, agent networks and mobile payments. Now, as the Nigerian fintech prepares for a potential New York Stock Exchange listing, its financial statements reveal a more consequential transformation: lending has overtaken payments as its largest source of revenue.
On October 9, 2026, OPay Limited filed a registration statement with the US Securities and Exchange Commission (SEC) for an initial public offering of American depositary shares. The company has applied to list on the New York Stock Exchange under the ticker symbol OPAY.
Market reports have put its potential valuation at approximately $4 billion, with a possible fundraising target of up to $500 million. Those figures remain estimates, however. OPay’s preliminary prospectus does not yet specify the final offer price, number of shares to be sold or expected proceeds.
The proposed listing arrives after a dramatic financial turnaround. OPay reported $536 million in revenue and $72.5 million in net profit in 2025, following a loss in 2024. In the first half of 2026, revenue rose to approximately $467.1 million, while net income reached $90.9 million.
For investors, the question is no longer simply whether OPay can attract users or process more payments. It is whether the company can turn its growing financial network into a durable, profitable lending business without allowing credit risk to undermine its growth.
The numbers behind OPay’s growth
OPay’s scale is central to its investment case.
According to its SEC filing, the company had approximately 50.1 million monthly active users and 26.8 million daily active users as of July 31, 2026. During the 12 months ended June 30, 2026, its platform processed approximately 90.1 billion transactions with a total transaction value of $558 billion.
Its physical distribution network remains equally important. OPay had deployed approximately 1.3 million point-of-sale terminals by June 30, of which around 800,000 were active.
These figures describe more than a mobile application. They represent a financial distribution network connecting consumers, merchants, agents and digital services at significant scale.
The revenue figures show how that network is being monetised.
In 2024, OPay generated $206 million in revenue and recorded a net loss of approximately $50.8 million. Revenue increased to $536 million in 2025, representing growth of roughly 161%, while the company reported a net profit of $72.5 million.
The momentum continued into 2026. For the six months ended June 30, revenue reached $467.1 million, compared with $197.5 million in the corresponding period of 2025. Net income increased to $90.9 million from approximately $21.7 million.
The company has therefore moved beyond a story based exclusively on user acquisition. It is reporting substantial revenue growth alongside profitability. The next question is how much of that performance comes from its core payments business—and how much depends on lending.
Source: OPay’s SEC registration statement.
The strategic pivot: payments are no longer the biggest revenue engine
The most important detail in OPay’s filing is the composition of its revenue.
In the first half of 2026, self-operated loan financing services generated approximately $236.1 million, accounting for 50.6% of total revenue. Transaction-based payment services generated approximately $130.6 million, or 28.0%.
Loan facilitation and other income streams contribute additional revenue. Including loan facilitation, credit-related activities account for close to 60% of OPay’s revenue.
This changes how investors should understand the company.
OPay’s payments infrastructure helps attract users, serve merchants and generate transaction activity. Its lending business then creates another opportunity to monetise those relationships through interest income and credit services.
The model has a compelling commercial logic: a company that already serves consumers and small businesses through payments may be better positioned to identify potential borrowers, distribute loans digitally and assess risk using transaction histories and other available information.
But a large user base does not automatically produce a strong lending business. The quality of underwriting, loan repayment behaviour, funding costs and the ability to manage defaults become increasingly important as credit expands.
OPay’s next phase will be judged not only by how much it lends, but by how consistently those loans generate returns after credit losses and operating costs.
From neighbourhood agents to digital financial infrastructure
OPay’s early advantage was distribution.
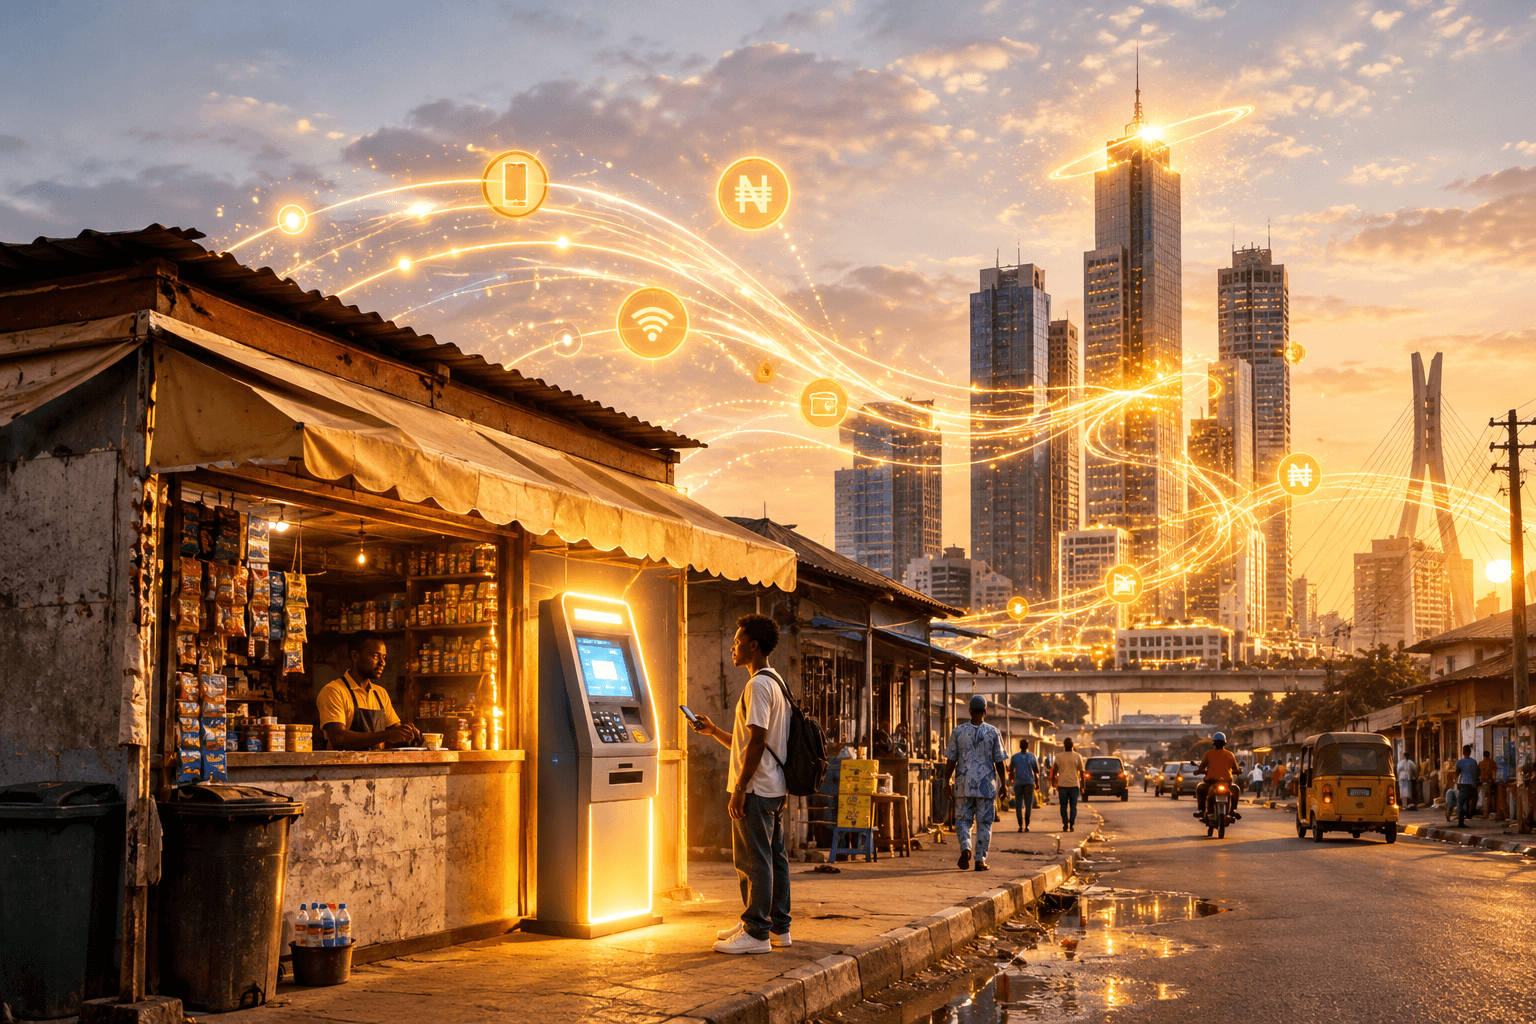
Rather than depending entirely on customers visiting conventional bank branches or adopting digital services without assistance, the company developed an agent network that allowed people to deposit and withdraw cash, transfer money and make payments through local businesses.
In practical terms, the model brought some banking functions closer to the communities that needed them.
OPay also experimented with services outside finance, including motorcycle ride-hailing and food delivery. Those businesses were subsequently scaled back as regulatory restrictions and the COVID-19 pandemic disrupted operations. The company refocused on financial services.
Nigeria’s 2023 currency redesign and resulting cash shortages further accelerated demand for digital payment alternatives. The episode exposed the difficulties of relying on physical cash while creating an opportunity for providers able to facilitate electronic transactions and cash access.
The structural opportunity extends beyond a single policy event. Across many African markets, gaps in conventional financial access have created room for mobile wallets, agency banking, merchant payments and digital credit.
OPay’s growth illustrates how a company can build a business around those gaps. Its agent network provides physical reach, its application connects users to services, and its transaction activity creates opportunities to expand its financial products.
However, the company’s scale should not be confused with continent-wide diversification. Nigeria remains the centre of its business, and that concentration has consequences for investors.
The credit-risk question investors cannot ignore
Lending can generate more revenue per customer than payment processing, but it introduces a different risk profile.
OPay’s expected credit-loss provisions rose substantially as its lending business expanded. The company reported approximately $118.4 million in expected credit-loss provisions for the first half of 2026, compared with approximately $38.1 million in the same period of 2025.
These provisions are accounting estimates of potential credit losses; they are not identical to the amount of loans already written off or ultimately lost.
Nevertheless, their increase is material. Expected credit-loss provisions grew faster than total revenue over the period, making credit quality an important issue for investors evaluating the company’s earnings.
A rapidly expanding loan book can increase reported income while simultaneously exposing a lender to greater future losses. The critical question is whether interest income and fees adequately compensate for defaults, funding costs and the operational expense of collecting repayments.
OPay will need to demonstrate that its risk-management systems can sustain growth without a disproportionate deterioration in loan performance.
Its digital distribution and transaction data may support underwriting, but those advantages must be demonstrated through repayment performance and risk-adjusted returns.
For prospective public-market investors, this is one of the central tests of the business.
A Nigerian business with a global capital-market ambition
OPay’s proposed listing also represents a significant development in the relationship between international capital and African financial technology.
The company attracted major investors during its private-market growth. In 2021, SoftBank Vision Fund II led a $400 million financing round that valued OPay at approximately $2 billion.
Its pre-IPO shareholder disclosures identify founder Zhou Yahui as a major beneficial owner, with approximately 21.3% ownership. Opera held approximately 8.6%, SoftBank entities approximately 6.6%, and IDG-linked entities approximately 6.0%, according to the reported ownership figures in the filing.
At an assumed $4 billion valuation, Zhou’s disclosed stake would imply a paper value of approximately $852 million before considering the final offer price, dilution, share-class arrangements or other transaction details. That is an illustrative valuation, not a confirmed sale value or cash payout.
The proposed IPO also comes with a potential African institutional investor.
According to the prospectus, Stanbic Africa Holdings Limited, part of Standard Bank Group, has agreed to subscribe for OPay shares in a concurrent private placement, subject to completion of the offering and applicable regulatory approvals. The subscription is subject to specified limits, including a maximum aggregate price of $200 million.
This arrangement could connect OPay more closely with a major African banking group while broadening its investor base. It should not, however, be interpreted as a completed investment before the transaction closes.
OPay has also indicated plans to pursue a secondary listing in Nigeria after its proposed US listing. If completed, the plan could give Nigerian investors a route to participate in the company’s public-market performance.
The broader significance is that a fintech built around local financial-access challenges is seeking access to international public capital while attracting interest from established African financial institutions.
What could go wrong?
Three risks deserve particular attention.
1. Nigeria concentration
Approximately 89.5% of OPay’s revenue came from Nigeria in the first half of 2026. This exposes the company to the naira’s exchange-rate movements, changes in monetary conditions, regulatory decisions and shifts in the Nigerian economy.
Its large user base is an advantage, but geographic concentration means that a significant change in its principal market could affect the group’s overall performance.
2. Lending quality
Credit-related activities now account for a majority of revenue when lending and loan facilitation are considered together. The rise in expected credit-loss provisions highlights the need to monitor loan performance alongside growth.
Investors should examine loan-book expansion, repayment trends, impairment charges, recoveries and risk-adjusted profitability rather than relying on revenue growth alone.
3. IPO pricing and market conditions
A successful filing does not guarantee a successful listing. Public-market investors must decide what valuation is justified by OPay’s earnings, risks, growth prospects and competitive position.
The approximately $4 billion valuation discussed in market reports remains an estimate until the offering terms are finalised. The final price will determine the valuation investors are actually being asked to accept.
What OPay’s trajectory means for Africa’s founders
OPay’s story offers a practical lesson for founders building financial and technology businesses across Africa.
The company did not begin by solving every financial problem at once. It developed distribution around everyday transactions, built relationships with users and merchants, and expanded its services as the network grew.
That progression matters because distribution can become a strategic asset. A business that consistently reaches customers, understands their needs and earns their trust may be able to introduce additional services more efficiently than a competitor starting from scratch.
But OPay’s lending pivot also demonstrates the limits of growth as a strategy. Entering a higher-revenue business does not automatically create a better business. The economics must remain sound after accounting for risk.
For founders in Kampala, Nairobi, Accra and other African markets, the lesson is twofold: build around a genuine access problem, and develop a monetisation model that can sustain itself over time.
For investors, OPay offers a different question. If the company’s payments network is now a foundation for lending, the value of the business depends on whether that combination can generate durable, risk-adjusted profits.
The WigWag view: the next test is earnings quality
OPay’s proposed NYSE listing is more than a fundraising event. It is a test of how public markets value an African fintech that has moved from payments distribution towards credit-led monetisation.
The company has demonstrated scale, rapid revenue growth and a return to profitability. Its next challenge is to show that those results can endure as lending becomes more important to the business.
Investors will need to assess not just how many customers OPay serves, how much money moves through its platform or how quickly revenue grows, but also the quality of its earnings, the resilience of its loan portfolio and the risks of operating in a heavily concentrated market.
A successful listing could strengthen the case for African financial-technology businesses seeking global capital. But the more important milestone will be what OPay proves after entering the public markets.
The question is not whether OPay can turn payments into lending. It already has. The question is whether it can turn that lending into sustainable earnings.
This article is for informational purposes only and does not constitute investment advice. IPO valuation and fundraising figures cited from market reports are estimates; final offering terms may differ.
Sources


Comments (0)